
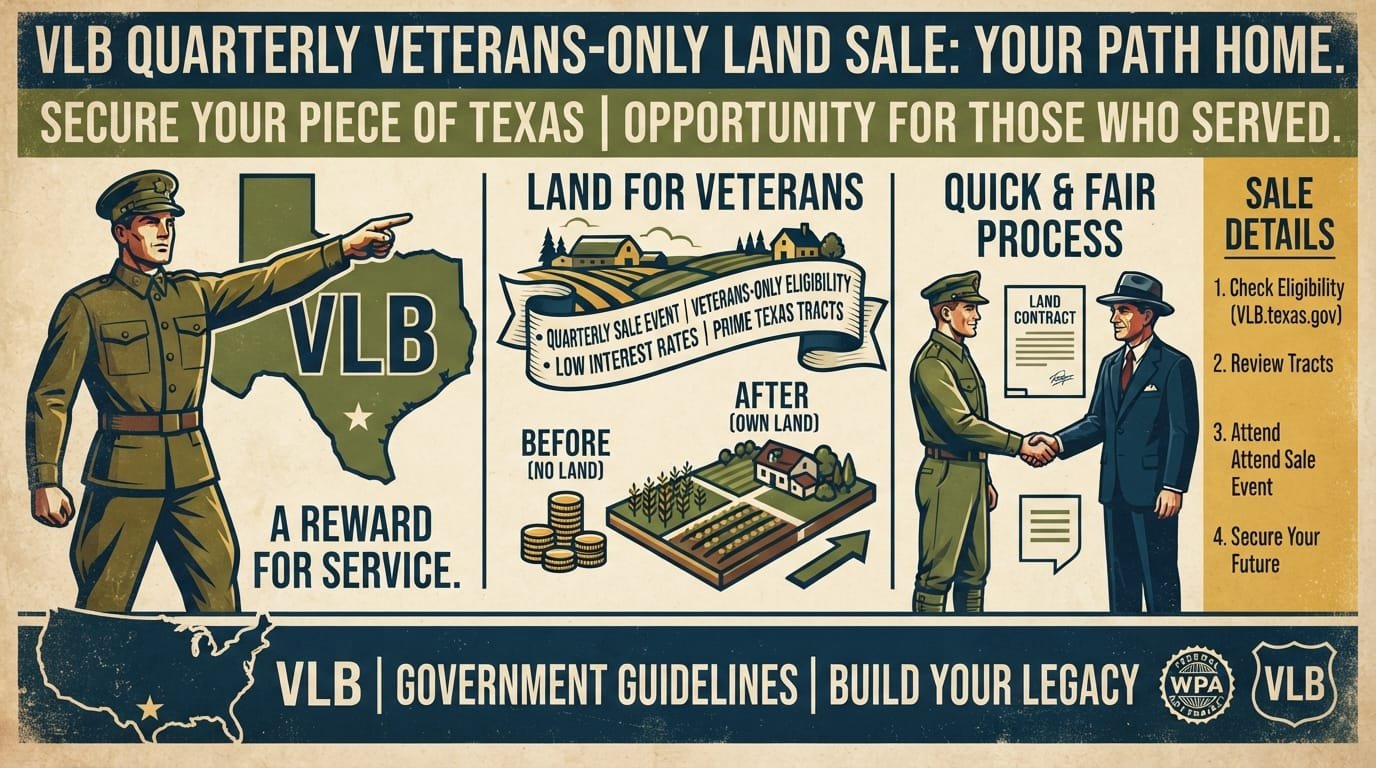
Texas Veterans Land Board: Loans and Eligibility Explained
The Texas Veterans Land Board (VLB) offers three loan programs to Texas veterans: the Veterans Land Loan Program (up to $200,000, 5% down), the Veterans Housing Assistance Program (VHAP, up to $806,500 with little or no down payment), and the Veterans Home Improvement Program (VHIP, up to $50,000). Applicants must be Texas residents with honorable service.
Quick Facts
| Item | Details |
|---|---|
| What It Is | State-run loan programs for Texas veterans and military members |
| Administered By | Texas General Land Office (GLO) / Veterans Land Board |
| Who Qualifies | Texas residents who are veterans, active duty, Guard/Reserve, or qualifying surviving spouses |
| Land Loan Maximum | $200,000 individual / $275,000 dual-spouse |
| Home Loan Maximum | $806,500 |
| Home Improvement Maximum | $50,000 |
| Application | VLB Forms 41, 42, and 43; then apply through a participating lender (home loans) or directly with VLB (land loans) |
| Processing Time | Varies by program and lender |
| Official Website | vlb.texas.gov |
| Hotline | 1-800-252-8387 |
| Updated For | 2026 |
What Is the Texas Veterans Land Board?
The Texas Veterans Land Board (VLB) is a state agency within the Texas General Land Office that administers loan programs and benefits exclusively for Texas veterans, military members, and their families. Established in 1946, the VLB operates the only state-level land loan program of its kind in the nation. It is funded entirely through bond issuances and loan repayments—no public taxpayer funding is used.

The VLB serves veterans through three core loan programs:
Veterans Land Loan Program — financing to purchase land in Texas
Veterans Housing Assistance Program (VHAP) — financing to purchase a primary residence in Texas
Veterans Home Improvement Program (VHIP) — financing for repairs and improvements to an existing home

Beyond loans, the VLB also operates Texas State Veterans Homes, Texas State Veterans Cemeteries, and the Voices of Veterans oral history program. This article focuses on the three loan programs, eligibility requirements, and how to apply in 2026.
Veterans Land Loan Program
The VLB Veterans Land Loan Program allows eligible Texas veterans to borrow up to $200,000 to purchase land at a competitive interest rate with a minimum 5% down payment. This program is the only one of its kind in the nation. It can be used to purchase non-commercial land that is one acre or more and meets VLB requirements.
Key Features
| Feature | Details |
|---|---|
| Maximum Loan Amount | $200,000 (individual); $275,000 (dual-spouse) |
| Minimum Down Payment | 5% |
| Loan Term | Up to 30 years |
| Interest Rate (2026) | 7.25% |
| Minimum Land Size | 1 acre |
| Maximum Land Size | 20 acres |
| Property Type | Non-commercial, raw or undeveloped land within Texas |
| Credit Approval | Required |
Dual-Spouse Land Loan Benefit
Two veterans who are married and individually eligible for the program may jointly apply for a land loan to purchase the same tract of land. Both spouses must satisfy all program qualification requirements. This benefit allows them to borrow up to $275,000 with a minimum 5% down payment.
How the Land Loan Works with VLB Land Sales
The VLB conducts quarterly Veterans-Only Land Sales every January, April, July, and October. The land is forfeited property managed by the state. Eligible veterans and military members may bid on available tracts. If a bid is accepted, the buyer may apply for a VLB Land Loan to finance the purchase.
Veterans May Qualify for Extra Benefits
Check available financial assistance, healthcare programs and other opportunities that may apply to you.
Check EligibilityImportant: The VLB will finance up to the minimum bid amount. Any amount offered over the minimum bid must be paid at closing. A $75 contract fee is required.
Land Loan Example
If the minimum bid is $120,000 and your winning offer is $125,000, the VLB will finance up to $114,000 (95% of the listed price). You would pay at closing:
5% down payment: $6,000
Amount over the listed price: $5,000
Total due at closing: $11,000
Veterans Housing Assistance Program (VHAP)
The Veterans Housing Assistance Program provides eligible Texas veterans with competitive, low-interest home loans of up to $806,500 with little or no down payment. VHAP is designed to assist veterans in purchasing a primary residence in Texas.
Key Features
| Feature | Details |
|---|---|
| Maximum Loan Amount | $806,500 |
| Down Payment | Little or no money down (varies by lender) |
| Loan Term | 15, 20, 25, or 30 years |
| Interest Rate (2026) | Base rate: 5.85%; Discounted rate: 5.35% |
| Disability Discount | 0.50% rate reduction for 30%+ VA disability rating |
| Property Types | Single-family (attached or detached), townhome, or condominium |
| Refinancing | Not allowed (except construction-to-permanent) |
| PMI | May be avoided when combined with VA benefits |
How VHAP Differs from a Standard VA Loan
VHAP is a state-level rate reduction program administered by the VLB. It is not a separate loan type—it is a rate subsidy applied to a standard VA-guaranteed, FHA, or conventional loan through VLB-participating lenders. The benefit is a below-market interest rate, typically 0.25–0.50 percentage points below the standard VA market rate.
Key point: You must work with a VLB-participating lender to access the VHAP rate. Not all VA-approved lenders offer the Texas Vet rate.
Property Requirements
To qualify for a VHAP loan, the property must:
Be wholly located in Texas
Be the veteran’s primary residence
Be a single-family home, townhome, or condominium
Remain the primary residence for at least 3 years
Be occupied within 60 days after loan closing
Meet energy efficiency standards for new construction (ENERGY STAR, HERS Index of 75 or less, or Energy Rating Index of 75 or less)
How the Interest Rate Discount Works
VLB sets a base rate that is 0.15% to 1.50% below the benchmark rate. Veterans with a VA service-connected disability rating of 30% or higher receive an additional 0.50% reduction. In FY2026, 96% of VLB home loan borrowers qualified for the discounted rate, and 50% were first-time homebuyers.
Veterans Home Improvement Program (VHIP)
The Texas Veterans Home Improvement Program (VHIP) provides below-market interest rate loans of up to $50,000 to qualified Texas veterans and military members for repairs and improvements to their existing homes. VHIP was introduced in 1986 and provides the same below-market interest rate as VHAP.
Key Features
| Feature | Details |
|---|---|
| Maximum Loan Amount | $50,000 |
| Loan Term | 2–20 years (for loans up to $50,000); 2–10 years (for loans $7,500–$10,000) |
| Interest Rate | Same base and discounted rates as VHAP |
| Disability Discount | 0.50% rate reduction for 30%+ VA disability rating |
| Property Types | Single-family dwellings, condominiums, duplexes, triplexes, four-plexes |
| Lien Position | VLB must be in first lien position for loans over $25,000 |
| Location | Home must be wholly located in Texas |
Eligible Improvements
VHIP loans can be used for a wide range of repairs and improvements, including:
Roof repair or replacement
HVAC systems
Foundation repairs
Accessibility modifications (ramps, widened doorways, grab bars)
Plumbing and electrical updates
Energy efficiency upgrades
Interior and exterior renovations
Current Demand
Home improvement loan demand has declined in recent years. In FY2026 Q2, the VLB issued 5 VHIP loans totaling $122,668—a 77.46% decrease in loan value from FY2025 Q2. Despite lower demand, the program remains available to eligible veterans.
VLB Eligibility Requirements
To qualify for any VLB loan program, you must be a Texas resident and meet one of several service criteria. Eligibility is based on Texas residency and military service, not on income limits.
Core Eligibility Requirements
| Requirement | Details |
|---|---|
| Age | At least 18 years old |
| Residency | Bona fide and legal resident of Texas on the date of application |
| Service | Must meet one of the service criteria below |
| Discharge | Honorable, general, or medical (dishonorable and certain other discharges not eligible) |
| Previous VLB Loans | Any previous VLB loan must be repaid; any active VLB loans must be in good standing |
Service Criteria: Who Qualifies
You meet the service requirement if you are:
An active-duty military member
A member of the Texas National Guard
A reserve component military member having completed 20 qualifying years for retirement
A veteran having served at least 90 active duty days (unless discharged sooner due to a service-connected disability and not discharged dishonorably)
A surviving spouse of a veteran listed as missing in action or whose death was service-connected
Discharge Requirements
Eligible discharge types: Honorable, General, Medical
Ineligible discharge types: Dishonorable, Bad Conduct, Other Than Honorable, Entry-Level Separation for Convenience of the Government.
Exception: A veteran with an ineligible discharge type may still qualify if they provide a Certificate of Eligibility from the U.S. Department of Veterans Affairs demonstrating they qualify for a USDVA loan based on service history.
No Income Limits
Unlike many federal housing programs, the VLB does not impose income limits on its loan programs. Creditworthiness is evaluated through VLB credit approval and lender underwriting.
Residency and Occupancy Rules
| Program | Residency Rule |
|---|---|
| Land Loan | Land must be within Texas; no occupancy requirement until you build |
| VHAP Home Loan | Primary residence for at least 3 years; occupy within 60 days of closing |
| VHIP Improvement | Home must be primary residence; home must be wholly in Texas |
How to Apply for VLB Loans
The application process differs depending on which VLB loan program you are using. Home loans (VHAP) are originated through participating lenders, while land loans and home improvement loans are applied for directly with the VLB.
Step 1: Confirm Your Eligibility
Before applying, gather your military service records:
DD-214 (Member 4 copy) for veterans
NGB-22 for National Guard members
Statement of Service for active-duty members
Certificate of Eligibility from VA if you have an ineligible discharge type
Request your military records through the National Archives at archives.gov if you do not have a copy.
Step 2: Complete VLB Certification Forms
Submit the following forms to the VLB:
| Form | Purpose |
|---|---|
| Form 41 | Request for Certification |
| Form 42 | Declaration of Eligibility |
| Form 43 | Affidavit of Texas Residency |
These forms can be downloaded from vlb.texas.gov or requested by calling 1-800-252-8387.
Step 3: Apply for Your Loan
For Land Loans: After your bid is accepted in a VLB land sale, you may apply for a VLB Land Loan directly with the VLB.
For VHAP Home Loans: Once you receive your Certification of Eligibility, contact a VLB-participating lender to begin the mortgage application. The lender will process your loan using VA, FHA, or conventional financing with the VHAP rate subsidy.
For VHIP Improvement Loans: Apply directly with the VLB. You will need:
Texas Driver’s License
Social Security Card
Proof of all income received
DD-214 Member 4 copy
Amount you want to borrow
Desired loan term (years)
Step 4: Credit Approval and Closing
All VLB loans are subject to credit approval. The loan amount is based on credit approval. For land loans, you will need to provide your most recent pay stubs to assist in determining your creditworthiness. For home loans, the participating lender handles underwriting and closing.
Processing Time
Processing times vary by program and lender. Land loans through VLB land sales follow the sale calendar (quarterly). Home loans follow standard mortgage timelines, typically 30–45 days. Home improvement loans are processed directly by VLB.
Comparison of VLB Loan Programs
| Feature | Land Loan | VHAP Home Loan | VHIP Improvement |
|---|---|---|---|
| Maximum Amount | $200,000 / $275,000 dual | $806,500 | $50,000 |
| Down Payment | 5% minimum | Little or none | N/A |
| Loan Term | Up to 30 years | 15, 20, 25, or 30 years | 2–20 years |
| Interest Rate (2026) | 7.25% | 5.85% base / 5.35% discounted | Same as VHAP |
| Property Type | 1–20 acres, non-commercial | Primary residence | Existing primary residence |
| Apply Through | VLB directly (after land sale bid) | VLB-participating lender | VLB directly |
| Refinancing | No | No (except construction-to-perm) | No |
| Disability Discount | No | Yes (30%+ rating) | Yes (30%+ rating) |
Combining VLB Loans with VA Benefits
Veterans can use VLB loans alongside federal VA benefits to maximize their purchasing power. The VLB and VA loan programs are separate and can be stacked strategically.
Common Stacking Strategies
| Strategy | How It Works |
|---|---|
| VA Loan + VLB Land Loan | Use a VA loan (0% down) for your primary home; use a VLB land loan (5% down) to purchase land separately |
| VLB Land Loan + VA Construction Loan | Purchase land with a VLB loan, then use VA construction financing to build on that land |
| VHAP + VA Entitlement | Use your VA entitlement with a VLB-participating lender to access the VHAP rate subsidy and possibly avoid PMI |
No Immediate Construction Requirement
The VLB Land Loan does not require you to build immediately. You can purchase land for long-term planning, future use, or retirement purposes and hold it without construction obligations.
Common Mistakes Veterans Make with VLB Loans
Many veterans miss out on VLB benefits because of avoidable mistakes. Here are the most common:
Not knowing the program exists. Only about 12% of eligible veterans take advantage of the VLB Land Loan Program.
Assuming VLB and VA are the same. VLB is a state program; VA is a federal program. They are separate and can be combined.
Working with a non-participating lender. For VHAP home loans, you must use a VLB-participating lender to access the rate subsidy.
Overlooking the 3-year occupancy rule. VHAP requires the home to remain your primary residence for at least 3 years—longer than the 1-year VA loan requirement.
Missing the 60-day move-in deadline. VHAP borrowers must occupy the home within 60 days after closing.
Bidding on land without understanding financing rules. The VLB finances only up to the minimum bid. Any amount over must be paid at closing.
Not gathering military records in advance. DD-214 or NGB-22 is required. Request it early from the National Archives.
Assuming income limits apply. VLB programs have no income limits, unlike many other housing assistance programs.
Not checking the current rate. VLB rates change weekly. Check vlb.texas.gov for the current rate before making decisions.
Missing the dual-spouse opportunity. Two eligible veteran spouses can borrow up to $275,000 for land—significantly more than the individual limit of $200,000.
Texas Veterans Land Board vs. TDHCA Programs
The VLB and the Texas Department of Housing and Community Affairs (TDHCA) serve different purposes. VLB focuses on land, home, and home improvement loans for veterans specifically. TDHCA administers broader affordable housing programs, including first-time homebuyer assistance, housing tax credits, and the Texas Homebuyer Program.
| Aspect | VLB | TDHCA |
|---|---|---|
| Focus | Veterans only | All Texans (some veteran preferences) |
| Loan Types | Land, home purchase, home improvement | Down payment assistance, tax credits, housing programs |
| Eligibility | Texas veterans, military, surviving spouses | Income-based for many programs |
| Income Limits | No | Yes, varies by program |
| Primary Benefit | Below-market rates for veterans | Affordable housing assistance |
Common Questions
1. What is the Texas Veterans Land Board?
The Texas Veterans Land Board (VLB) is a state agency within the Texas General Land Office that administers loan programs for Texas veterans, military members, and their families. It offers land loans, home loans, and home improvement loans at below-market interest rates.
2. Who is eligible for VLB loans?
You must be at least 18, a bona fide Texas resident on the application date, and meet one of these criteria: active duty, Texas National Guard, Reserve with 20 qualifying years, or a veteran with at least 90 days active duty (unless discharged sooner due to service-connected disability). Surviving spouses of MIA or service-connected deceased veterans also qualify.
3. What is the maximum VLB land loan amount in 2026?
The maximum is $200,000** for individual eligible veteran borrowers and **$275,000 for two veteran spouses who are both individually eligible. This represents an increase from the previous limits of $150,000 and $225,000, effective February 9, 2026.
4. How much can I borrow through VHAP?
The Veterans Housing Assistance Program allows eligible veterans to receive up to $806,500 on a fixed-rate loan for 15, 20, 25, or 30-year terms. The loan can be used with VA, FHA, or conventional financing through a VLB-participating lender.
5. What is the current VLB home loan interest rate?
As of 2026, the VHAP base rate is 5.85%, with a discounted rate of 5.35% for veterans with a VA service-connected disability rating of 30% or higher. VLB rates change weekly and should be verified at vlb.texas.gov.
6. What is the current VLB land loan interest rate?
The current land loan interest rate is 7.25% for a 30-year term with a minimum 5% down payment. Rates are subject to change.
7. Do I need a down payment for a VLB loan?
Land loans require a minimum 5% down payment. VHAP home loans offer little or no down payment options. VHIP improvement loans do not require a down payment as they are secured against your existing home equity.
8. Can I use my VA loan with a VLB loan?
Yes. VLB programs are separate from federal VA loans and can be used together. You can use a VA loan for your primary home and a VLB land loan to purchase land separately. You can also use VHAP with your VA entitlement through a participating lender.
9. What is the Veterans Home Improvement Program?
VHIP provides below-market interest rate loans of up to $50,000 for repairs and improvements to an existing primary residence. Eligible improvements include roofing, HVAC, foundation repairs, accessibility modifications, and energy efficiency upgrades.
10. How do I apply for a VLB loan?
First, complete VLB Forms 41 (Request for Certification), 42 (Declaration of Eligibility), and 43 (Affidavit of Texas Residency). For land loans, bid in a VLB land sale and then apply for financing. For VHAP home loans, contact a VLB-participating lender. For VHIP, apply directly with the VLB.
11. Are there income limits for VLB loans?
No. Unlike many affordable housing programs, VLB loan programs do not impose income limits. Eligibility is based on Texas residency, military service, and credit approval.
12. What discharge types are eligible for VLB loans?
Eligible discharges are honorable, general, and medical. Dishonorable, bad conduct, other than honorable, and entry-level separation discharges are not eligible unless the veteran provides a VA Certificate of Eligibility demonstrating qualification for a USDVA loan.
13. What is the dual-spouse land loan benefit?
Two veterans who are married and individually eligible for the VLB Land Loan Program may jointly apply for a loan to purchase the same tract of land. Both must satisfy all qualifications. This allows them to borrow up to $275,000 with a 5% minimum down payment.
14. How often does VLB hold land sales?
The VLB holds quarterly Veterans-Only Land Sales every January, April, July, and October. Available tracts are posted online at vlb.texas.gov. Bidding periods typically run for about six weeks.
15. Does VLB offer refinancing?
No. The VLB does not offer refinancing through VHAP. It cannot provide refinancing to lower an existing interest rate, and the program cannot be used for a down payment on a home. Refinances are not allowed except construction-to-permanent financing not exceeding 24 months.
Key Takeaways
The Texas Veterans Land Board (VLB) is a state agency offering land, home, and home improvement loans to Texas veterans.
VLB Land Loan: Up to $200,000 ($275,000 dual-spouse), 5% down, 1–20 acres, 7.25% interest rate in 2026.
VHAP Home Loan: Up to $806,500, little or no down payment, 5.85% base rate / 5.35% discounted rate.
VHIP Improvement Loan: Up to $50,000 for repairs and upgrades to an existing home.
Eligibility requires Texas residency and qualifying military service. No income limits apply.
Veterans with a 30%+ VA disability rating receive an additional 0.50% rate discount on home and improvement loans.
VLB programs can be combined with VA loans for maximum purchasing power.
Apply using VLB Forms 41, 42, and 43. Home loans are originated through VLB-participating lenders.
Only about 12% of eligible veterans use the VLB Land Loan Program — many miss out on this benefit.
Contact the VLB at 1-800-252-8387 or visit vlb.texas.gov for current rates and applications.
Official Resources
Texas Veterans Land Board: vlb.texas.gov
Texas General Land Office: glo.texas.gov
VLB Loan Application Forms: vlb.texas.gov/loans
VLB Land Sales: vlb.texas.gov/land
VLB Hotline: 1-800-252-8387
U.S. Department of Veterans Affairs (VA): va.gov
VA Home Loan Program: va.gov/housing-assistance/home-loans
National Archives (Military Records): archives.gov
USA.gov Veterans Benefits: usa.gov/veterans-benefits
Veterans Crisis Line: Dial 988, then press 1

🇺🇸 IMPORTANT DISCLAIMER – Veterans Benefits Information
This site provides general information about U.S. Department of Veterans Affairs (VA) benefits for educational and informational purposes only.
- Not Official: We are NOT affiliated with, endorsed by, or connected to the U.S. Department of Veterans Affairs (VA), the Veterans Benefits Administration (VBA), the Veterans Health Administration (VHA), or any other government agency.
- No Legal/Financial Advice: The content on this website is for informational purposes only and does not constitute legal, financial, or medical advice. VA benefits rules change frequently – always consult with an accredited Veterans Service Officer (VSO) or a qualified professional for your specific situation.
- Official Sources: For official, binding information and to apply for benefits, always visit official .gov websites: VA.gov, Benefits.VA.gov, or SSA.gov.
- No Data Collection: This site does not collect, store, or process any personal information. It does not have login forms, contact forms, or any system to capture user data. We never ask for your Social Security Number, bank details, or any personal information.
- 🚨 Scam Alert: The VA and other government agencies never charge fees for benefit applications. If anyone asks for money to "process" your VA claim, it is a scam. Report it to the VA Office of Inspector General at VA.gov/OIG.
- Advertising: This site uses third-party advertising (Adsterra) to cover operational costs. We do not endorse or guarantee any products or services advertised.
📌 Information provided as of June 2026. Always verify current eligibility and rules with official .gov sources.
This site is not affiliated with the U.S. Department of Veterans Affairs or any government agency. All information is for educational purposes only. Please visit VA.gov for official information.
