
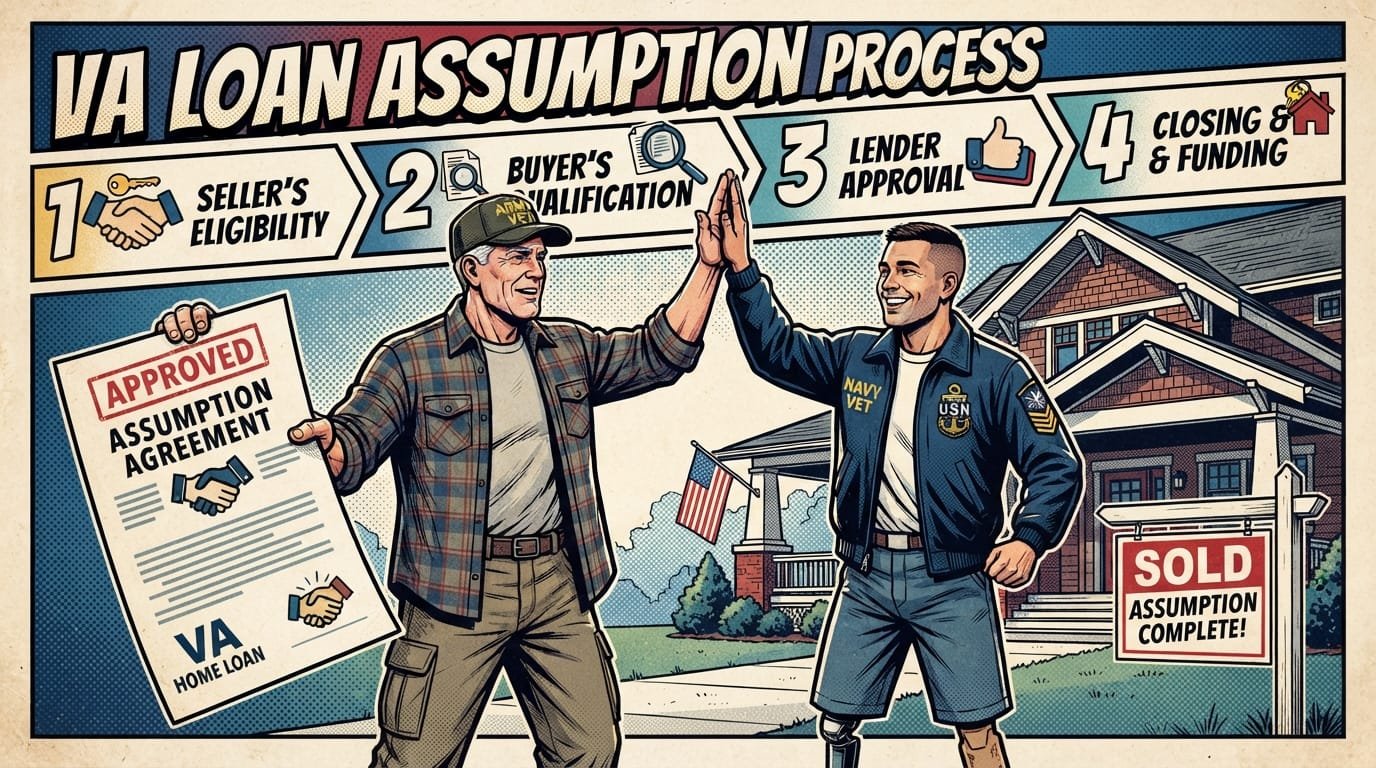
Are VA Loans Assumable? The Complete 2026 Guide for Veterans and Buyers
Yes. VA loans are assumable by qualified buyers, including non-veterans, with approval from the loan servicer and the U.S. Department of Veterans Affairs. The buyer takes over the existing loan’s interest rate, term, and remaining balance. A 0.5% VA funding fee applies. Loans originated after March 1, 1988 require VA approval.
Quick Facts
| Item | Details |
|---|---|
| Benefit | Buyer assumes the seller’s existing VA loan at the original interest rate and term |
| Eligibility (Buyer) | Any qualified buyer, including non-veterans; credit score typically 620+; DTI generally 41% or lower |
| Eligibility (Loan) | VA loans originated after March 1, 1988 are assumable with VA approval |
| Application | Through the loan servicer; VA Form 26-6381 for release of liability |
| Processing Time | Servicer decision within 45 days of complete package; VA submission within 35 days if no automatic authority |
| Official Agency | U.S. Department of Veterans Affairs (VA) |
| Required Forms | VA Form 26-6381, VA Form 26-6807, VA Form 26-8106 (if substituting entitlement) |
| Funding Fee | 0.5% of the loan balance, due within 15 days of assumption |
| Updated For | 2026 loan limits and funding fee rates |
What Is a VA Loan Assumption?
A VA loan assumption is a transaction where a buyer takes over the seller’s existing VA-guaranteed mortgage. The buyer becomes responsible for the remaining loan balance and makes payments to the same servicer. The loan’s interest rate, repayment term, and remaining principal balance stay unchanged.

This differs from a new VA loan, where the buyer applies for fresh financing with current market rates. With an assumption, the buyer steps into the seller’s existing loan terms.

Why it matters: If the seller’s VA loan has a low interest rate, the buyer can save substantially compared to obtaining a new mortgage at today’s rates. The VA loan program is one of the few mortgage products that is broadly assumable by non-veterans.
Who Qualifies to Assume a VA Loan?
Any qualified buyer can assume a VA loan, including non-veterans, provided they meet the servicer’s credit and income standards. There is no requirement that the assumer be a veteran or military member.
The VA does not set specific credit score or debt-to-income (DTI) minimums for assumptions, but most loan servicers apply their own underwriting standards. Common requirements include:
Credit score: Typically 620 or higher. Some servicers accept 580–600 with compensating factors.
Debt-to-income ratio: Generally 41% or lower. VA guidelines treat 41% as a benchmark, not a hard cutoff, and exceptions may be made for strong compensating factors.
Income verification: Proof of stable income sufficient to cover the assumed mortgage payment plus other debts.
Loan current: The existing VA loan must be current (not delinquent) at the time of assumption.
Occupancy (for entitlement substitution): If the assumer wants the seller’s entitlement restored through substitution, the assumer must be an eligible veteran who will occupy the property as their primary residence.
Important: For loans originated on or before March 1, 1988, VA approval is not required. These older loans can be assumed without VA involvement. For loans originated after March 1, 1988, VA approval is mandatory.
How the Assumption Process Works
Veterans May Qualify for Extra Benefits
Check available financial assistance, healthcare programs and other opportunities that may apply to you.
Check EligibilityThe assumption process is servicer-driven. The buyer does not apply directly to the VA. Instead, the buyer works with the seller’s loan servicer, who evaluates the buyer’s creditworthiness and processes the assumption package.
Step-by-Step Process
Confirm the loan is assumable. Contact the loan servicer and verify the loan was originated after March 1, 1988 (or confirm it qualifies under pre-1988 rules if applicable).
Submit a complete assumption package. This typically includes a credit application, income documentation, and asset verification. The servicer reviews the buyer’s financial profile.
Servicer decision. Servicers with automatic authority must render a decision within 45 calendar days of receiving a complete application package.
VA submission (if required). Servicers without automatic authority must submit the assumption application to the VA for prior approval within 35 calendar days of receiving a complete package.
Pay the VA funding fee. The 0.5% funding fee is due within 15 days of the assumption. Some veterans may be exempt from this fee.
Execute the assumption agreement. Once approved, the buyer signs the assumption agreement and the deed is transferred.
Release of liability (optional). The seller may apply for a release of liability using VA Form 26-6381. This releases the seller from personal liability to the government on the loan.
Understanding VA Entitlement and Assumptions
VA entitlement is the benefit that allows veterans to obtain a VA loan without a down payment and without private mortgage insurance. When a veteran takes out a VA loan, their entitlement is tied to that specific loan.
Critical point: When a buyer assumes a VA loan, the veteran seller’s entitlement remains tied to the loan until the loan is fully paid off—unless the assumer substitutes their own entitlement (if eligible).
Entitlement Restoration Options
There are two primary paths to restore the veteran seller’s entitlement:
1. Substitution of Entitlement
If the assumer is an eligible veteran who will occupy the property as their primary residence and has sufficient available entitlement, they can substitute their entitlement for the seller’s. This restores the seller’s entitlement, allowing them to use it again.
2. Full Loan Payoff
The seller’s entitlement is restored when the assumed loan is paid in full—either through the new borrower’s refinance or through the eventual payoff of the balance.
One-time restoration: In certain circumstances, a veteran may request a one-time restoration of entitlement without selling the home or paying off the original loan. This is subject to VA approval and specific conditions.
Important: Entitlement is not automatically restored with an approved assumption or release of liability. The veteran must apply for restoration, and the VA must process a determination of eligibility.
VA Funding Fee for Assumptions
The VA funding fee for a loan assumption is 0.5% of the loan balance. This is significantly lower than the standard VA funding fee for new purchase loans, which ranges from 2.15% to 3.3% depending on down payment and prior use.
| Scenario | VA Funding Fee |
|---|---|
| New VA purchase (first use, 0% down) | 2.15% |
| New VA purchase (subsequent use, 0% down) | 3.3% |
| VA loan assumption | 0.5% |
The fee is due within 15 days of the assumption. The servicer typically collects it and forwards it to the VA.
Exemptions: Veterans receiving VA disability compensation, surviving spouses, and certain other categories may be exempt from the VA funding fee. Check with the loan servicer or VA to confirm exemption status.
Required Documents and Forms
| Form | Purpose |
|---|---|
| VA Form 26-6381 | Application for Assumption Approval and/or Release from Personal Liability |
| VA Form 26-6807 | Financial Statement |
| VA Form 26-8106 | Statement of Veteran Assuming GI Loan (for entitlement substitution cases) |
| Certificate of Eligibility (COE) | Required for both veteran seller and veteran assumer in substitution cases |
The buyer provides standard financial documentation: pay stubs, tax returns, bank statements, and identification. The servicer may request additional documentation based on the buyer’s financial profile.
Common Mistakes to Avoid
1. Assuming VA entitlement transfers automatically.
Many veterans believe that selling their home via assumption automatically restores their entitlement. It does not. Entitlement restoration requires a separate application and, in most cases, either a substitution of entitlement by a veteran buyer or full payoff of the loan.
2. Ignoring the equity gap.
The buyer must cover the difference between the purchase price and the remaining loan balance. For example, if the home sells for $400,000 and the remaining VA loan balance is $280,000, the buyer needs $120,000 in cash or secondary financing. This is the most common obstacle in assumption transactions.
3. Assuming any servicer will process an assumption.
Not all servicers are equally experienced with assumptions. Some may be slow or unfamiliar with VA-specific requirements. Before entering a purchase agreement, confirm the servicer’s assumption process and timeline.
4. Forgetting the funding fee.
The 0.5% assumption funding fee is due within 15 days. Budget for this cost at closing.
5. Failing to obtain a release of liability.
If the veteran seller wants to be released from personal liability, they must complete VA Form 26-6381. Without this release, the veteran remains liable if the assumer defaults.
VA Loan Assumption with Secondary Financing
Buyers who cannot cover the equity gap in cash may use secondary financing—a second mortgage or home equity line of credit—to bridge the difference. The VA clarified in Circular 26-24-17 that it does not prohibit an assumer from obtaining secondary financing when assuming a VA-guaranteed loan.
Key points:
The VA loan remains in first lien position.
The secondary loan does not need to be assumable.
The second mortgage creates a second monthly payment.
The buyer’s DTI must still qualify with both payments included.
Example: Home price $400,000. Remaining VA loan balance $280,000. Equity gap $120,000. The buyer assumes the $280,000 VA loan and takes a $120,000 second mortgage to cover the gap. Both payments are included in DTI calculations.
VA Loan Assumability by Loan Date
| Loan Origination Date | VA Approval Required? | Notes |
|---|---|---|
| Before March 1, 1988 | No | Loan is freely assumable; VA approval not required |
| After March 1, 1988 | Yes | VA approval and servicer approval required |
| After March 1, 1988 (with substitution) | Yes | Veteran assumer may substitute entitlement to restore seller’s entitlement |
This date distinction is critical. Pre-1988 VA loans are freely assumable without VA involvement, but these loans are rare in today’s market. The vast majority of existing VA loans were originated after 1988 and require approval.
Pros and Cons of Assuming a VA Loan
| Pros | Cons |
|---|---|
| Lower interest rate (if seller’s rate is below market) | Large cash requirement for equity gap |
| Lower funding fee (0.5% vs. 2.15%–3.3%) | Servicer approval required; can take 45+ days |
| No appraisal required in many cases | Seller’s entitlement remains tied up unless substituted or paid off |
| No new loan origination costs | Limited availability; not all sellers have assumable loans |
| Faster closing in some cases | Servicer may be unfamiliar with assumption process |
Recent Rule Changes and Updates (2025–2026)
Secondary financing guidance (August 2024): VA Circular 26-24-17 confirmed that assumers may use secondary financing to cover the equity gap without violating VA requirements. The secondary loan does not need to be assumable.
Assumption processing fee: The maximum charge for processing an assumption application is the lesser of $300 or the actual cost of any credit report required. This fee may be charged by the servicer with automatic authority.
Proposed funding fee increase: Congress has considered legislation that would raise the VA assumption funding fee from 0.5% to 1.0%. As of 2026, the 0.5% rate remains in effect unless new legislation is enacted.
Processing timelines: Servicers with automatic authority must decide on a complete assumption package within 45 calendar days. Servicers without automatic authority must submit to VA within 35 days.
Common Questions
Are VA loans assumable by non-veterans?
Yes. Any qualified buyer, including non-veterans, can assume a VA loan. The buyer must meet the servicer’s credit and income requirements. The veteran seller’s entitlement remains tied to the loan unless substituted or paid off.
Can a veteran use their VA loan again after an assumption?
Only if entitlement is restored. This requires either a substitution of entitlement by a veteran assumer or full payoff of the assumed loan. Entitlement is not automatically restored.
What credit score do I need to assume a VA loan?
The VA does not set a minimum, but most servicers require a 620 FICO score. Some accept 580–600 with compensating factors. Check with the specific servicer.
How much is the VA funding fee for an assumption?
The funding fee is 0.5% of the loan balance. This is due within 15 days of the assumption. Some veterans may be exempt.
Can I assume a VA loan with no down payment?
Yes, if you can cover the equity gap between the purchase price and the remaining loan balance. The equity gap is the difference the buyer must pay in cash or through secondary financing.
What happens to the seller’s entitlement after an assumption?
The seller’s entitlement remains tied to the loan until it is paid off or substituted by a veteran assumer. The seller cannot use that entitlement for another VA loan until it is restored.
Can a non-veteran spouse assume a VA loan?
A non-veteran spouse may assume the loan, but entitlement substitution is not available unless the assumer is a veteran. The veteran seller’s entitlement remains tied to the loan.
How long does a VA loan assumption take?
Servicers with automatic authority must decide within 45 days of a complete package. VA processing may add additional time if the servicer lacks automatic authority.
What forms are required for a VA loan assumption?
VA Form 26-6381 (Application for Assumption Approval), VA Form 26-6807 (Financial Statement), and VA Form 26-8106 (for entitlement substitution cases).
Are there closing costs on a VA loan assumption?
Yes. The buyer typically pays the 0.5% funding fee, a servicer processing fee of up to $300, title fees, and recording fees. Closing costs are generally lower than a new mortgage.
Can I assume a VA loan if the seller is behind on payments?
No. The loan must be current at the time of assumption. Delinquent loans are not eligible for assumption.
What is a release of liability?
A release of liability removes the veteran seller from personal liability on the VA loan. It is obtained through VA Form 26-6381. Without it, the seller remains liable if the buyer defaults.
Key Takeaways
VA loans originated after March 1, 1988 are assumable with VA and servicer approval.
Any qualified buyer, including non-veterans, can assume a VA loan.
The buyer takes over the seller’s interest rate, term, and remaining balance.
The VA funding fee for an assumption is 0.5% of the loan balance, due within 15 days.
The veteran seller’s entitlement remains tied to the loan unless substituted by a veteran assumer or the loan is paid off.
Entitlement restoration is not automatic; it requires a separate application.
Most servicers require a 620 credit score and a DTI of 41% or lower.
Buyers must cover the equity gap with cash or secondary financing.
Servicers with automatic authority must decide within 45 days.
Pre-1988 VA loans are freely assumable without VA approval.
Official Resources
VA Loan Assumption Information: VA.gov – Loan Assumptions
VA Form 26-6381: Application for Assumption Approval and/or Release from Personal Liability
VA Form 26-6807: Financial Statement
VA Form 26-8106: Statement of Veteran Assuming GI Loan
VA Funding Fee Information: VA.gov – Funding Fee and Closing Costs
VA Regional Loan Center (RLC): Contact the RLC with jurisdiction over the property location for assumption questions.
Consumer Financial Protection Bureau: CFPB – Mortgages for general mortgage guidance.

🇺🇸 IMPORTANT DISCLAIMER – Veterans Benefits Information
This site provides general information about U.S. Department of Veterans Affairs (VA) benefits for educational and informational purposes only.
- Not Official: We are NOT affiliated with, endorsed by, or connected to the U.S. Department of Veterans Affairs (VA), the Veterans Benefits Administration (VBA), the Veterans Health Administration (VHA), or any other government agency.
- No Legal/Financial Advice: The content on this website is for informational purposes only and does not constitute legal, financial, or medical advice. VA benefits rules change frequently – always consult with an accredited Veterans Service Officer (VSO) or a qualified professional for your specific situation.
- Official Sources: For official, binding information and to apply for benefits, always visit official .gov websites: VA.gov, Benefits.VA.gov, or SSA.gov.
- No Data Collection: This site does not collect, store, or process any personal information. It does not have login forms, contact forms, or any system to capture user data. We never ask for your Social Security Number, bank details, or any personal information.
- 🚨 Scam Alert: The VA and other government agencies never charge fees for benefit applications. If anyone asks for money to "process" your VA claim, it is a scam. Report it to the VA Office of Inspector General at VA.gov/OIG.
- Advertising: This site uses third-party advertising (Adsterra) to cover operational costs. We do not endorse or guarantee any products or services advertised.
📌 Information provided as of June 2026. Always verify current eligibility and rules with official .gov sources.
This site is not affiliated with the U.S. Department of Veterans Affairs or any government agency. All information is for educational purposes only. Please visit VA.gov for official information.
